Editorial Visual • D BIZ Insights
On this page
Navigating GST Input Tax Credit (ITC)
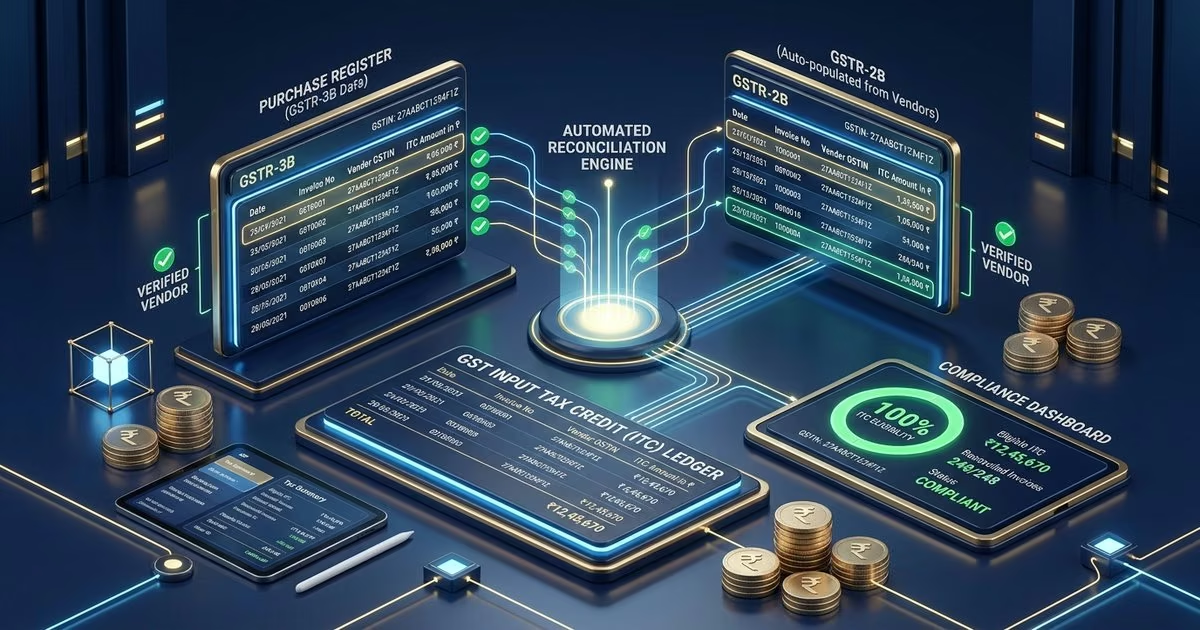
Claiming Input Tax Credit is the lifeblood of working capital management. However, recent amendments under Section 16(2)(aa) of the CGST Act strictly forbid claiming provisional credit unless the invoice is reflected in GSTR-2B.
Key Conditions to Claim Eligible ITC (Section 16)
- Possession of Tax Invoice or Debit Note: Issued by a registered supplier.
- Actual Receipt of Goods or Services: Delivery chalans or job-work proofs must be maintained.
- Tax Paid by Supplier: Supplier must have filed GSTR-3B and remitted tax to the government.
- Filing of Return (GSTR-3B): By the recipient on or before the statutory due date.
- Payment within 180 Days: If payment is not released to the vendor within 180 days, ITC must be reversed along with interest under Section 50.
Common Reasons for DRC-01 Notices
- Discrepancy between GSTR-3B (Table 4) and GSTR-2B auto-populated statement.
- Ineligible ITC claimed on blocked credits under Section 17(5) (e.g. personal motor vehicles, corporate food & beverages).
- Invoices reported by canceled or suspended GSTINs.
Best Practices for Businesses
- Run automated monthly 2B reconciliations prior to releasing vendor payments.
- Maintain vendor compliance scoring: hold 5% retention for irregular GST filers.
Topics Covered:#GST#Input Tax Credit#GSTR-2B#DRC-01#Tax Compliance
Written by
Akash P R
Business Consultant10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances • D BIZ CONSULTANCY
Business Consultant with 10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances.
First Published: 18 September 2026•Last Updated: 21 October 2026
Connect with Akash on LinkedInEditorial & Regulatory Standard: Every guide is rigorously fact-checked against current MCA V3 notifications, Central/State GST amendments, and the Kerala Stamp Act by empanelled Chartered Accountants, Company Secretaries, and Corporate Lawyers.