GST Registration Cancellation: Treatment of Closing Stock, Capital Goods and Input Tax Credit Reversal
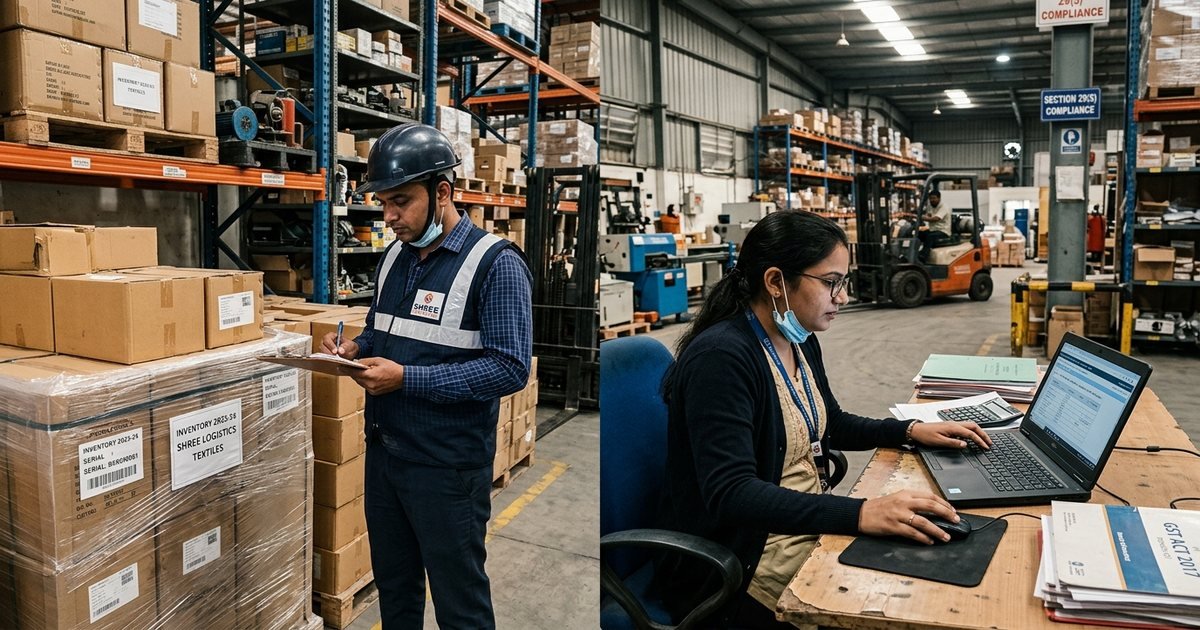
When a business cancels or surrenders its GST registration under Section 29 of the CGST Act, it must discharge an amount equal to the Input Tax Credit (ITC) attributable to inputs held in stock, inputs contained in semi-finished/finished goods, and capital goods, or the output tax payable on such goods, whichever is higher, as mandated by Section 29(5). For capital goods, ITC reversal is calculated by reducing the credit originally claimed by 5% per quarter of useful life. The taxpayer must pay this liability and file Form GSTR-10 (Final Return) within 3 months of the cancellation order.
Winding Down a GST Registration: Managing Closing Stock & ITC Reversal
Whether closing down operations, restructuring into a corporate entity, or surrendering an unnecessary registration, canceling a GSTIN is not simply a matter of clicking "Cancel Registration" on the GST portal.
Under Section 29(5) of the CGST Act, 2017, any registered person whose registration is cancelled is legally required to pay an amount equal to the Input Tax Credit (ITC) on inventory and capital assets held on the day immediately preceding the cancellation, or the output tax payable on such goods, whichever is greater.
Review our corporate advisory solutions on GST Filings & Cancellation.
1. Section 29(5) CGST Act: The Dual Valuation Rule
When calculating your settlement liability upon GST cancellation, evaluate:
Tax Liability = Higher of [ITC attributable to inputs & capital goods, OR Output tax payable on transaction value]
| Asset Classification | Reversal Valuation Methodology | Applicable Rule |
|---|---|---|
| Raw Materials & Inputs in Stock | Actual ITC availed on the invoice; if invoices missing, fair market value | Rule 44(1)(a) |
| Semi-finished / Finished Goods | Proportionate ITC availed on the inputs contained in those finished products | Rule 44(1)(b) |
| Capital Goods & Plant/Machinery | Total ITC availed reduced by 5% per quarter of life elapsed, OR transaction value tax | Rule 44(2) & Rule 44(6) |
2. Capital Goods Useful Life Calculation Formula
Under GST law, the useful life of capital goods is presumed to be 5 years (60 months or 20 quarters) from the date of invoice.
Step-by-Step Capital Goods Reversal Example:
- A manufacturing firm in Trivandrum purchased machinery for ₹10,00,000 + ₹1,80,000 IGST (18%) on 1 January 2024.
- The company applies for GST cancellation on 1 October 2026.
- Elapsed period: 11 quarters.
- Credit reduction: 11 quarters * 5% = 55%.
- Remaining percentage: 100% - 55% = 45%.
- ITC to be reversed: 45% of ₹1,80,000 = ₹81,000.
- If the machine is scrapped or sold for ₹2,00,000 (tax = ₹36,000), the firm must pay the higher amount: ₹81,000.
3. The 3-Step Cancellation & GSTR-10 Roadmap
- Step 1: File Form GST REG-16 (Voluntary Cancellation) - Specify grounds for cancellation (transfer of business, death of proprietor, turnover below threshold) and date from which cancellation is sought.
- Step 2: Issuance of Cancellation Order (Form GST REG-19) - Jurisdictional officer verifies clearances and issues formal cancellation order.
- Step 3: File Final Return Form GSTR-10 within 3 Months - Complete mandatory closing stock reporting and liability discharge.
Essential Requirements for Form GSTR-10:
- Detail closing stock quantities, invoice numbers, tax values, and reversing tax amounts in Table 8.
- For certified accounts where invoice copies are older than 5 years or unidentifiable, attach a Chartered Accountant or Cost Accountant valuation certificate.
- Discharge the liability via Table 9 using available electronic credit ledger balances or electronic cash ledger deposits.
4. Risks of Ignoring GSTR-10 Compliance
Many founders assume that once the cancellation order (Form GST REG-19) is issued by the jurisdictional officer, their GST obligations end. This is a critical misconception:
- The GST system continuously tracks the 3-month statutory window for GSTR-10.
- Default triggers a formal notice in Form GSTR-3A.
- If ignored, the proper officer can invoke best-judgment assessment under Section 62, creating unilateral tax demands based on historical turnover and freezing promoter personal bank accounts.
For compliant business closure, GST surrenders, and final returns, consult the D BIZ Indirect Tax Desk.
Frequently Asked Questions
Akash P R
Business Consultant10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances • D BIZ CONSULTANCY
Business Consultant with 10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances.
Connect with Akash on LinkedInOther Strategic Business Guides
GST Registration Documents in Kerala: How to Avoid Application Rejection
8 min readGST & TaxationGSTR-2B Reconciliation with Purchase Register: How to Match Invoices and Protect ITC
9 min readCompany Law & MCAAOC-4 vs MGT-7: Annual MCA Filing Requirements for Indian Companies Explained
8 min readLLP ComplianceLLP Form 8 and Form 11: Annual Compliance Checklist, Timelines and Late Fee Risks
7 min readLatest Regulatory Bulletins
Speak With Our Senior Business Consultants in Trivandrum & Kochi
D BIZ CONSULTANCY PVT. LTD. provides end-to-end company formation, ROC filings, GST accounting, trademark protection, and statutory compliance. Connect with us for personal advisory at our physical offices or 100% paperless digital onboarding.