Profit vs Cash Flow: Why Profitable Businesses Fail and How to Manage Working Capital
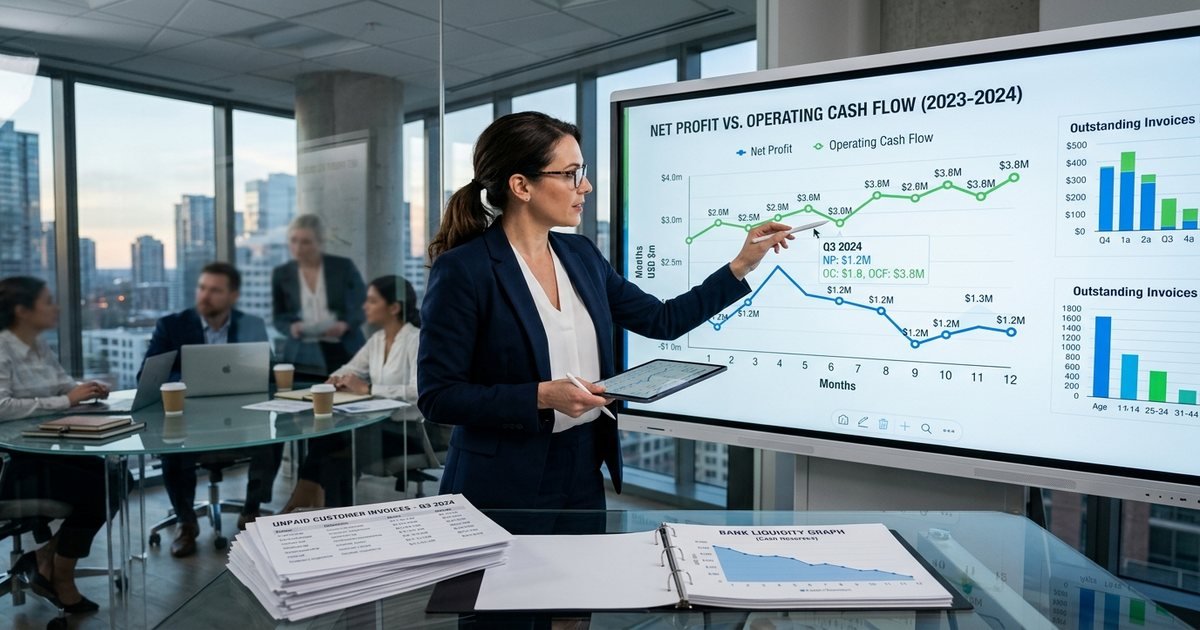
Profit and Cash Flow measure entirely different dimensions of business health. Profit is an accounting metric calculated on an accrual basis (Revenue earned minus Expenses incurred), regardless of whether cash has actually been collected. Cash Flow measures the real physical inflow and outflow of liquid money through the company's bank accounts. A company can report record net profits on paper but still suffer insolvency and bankruptcy if customer receivables are delayed while rent, salaries, loan EMIs, and GST liabilities require immediate cash.
The Profit-Liquidity Paradox: Why Profitable Companies Go Bankrupt
There is an old financial adage that holds true for every enterprise: *"Profit is vanity, cash flow is sanity, but cash in hand is reality."*
Every year, numerous commercial enterprises in India reporting robust operating profits on their Profit & Loss statements find themselves unable to meet basic operational payroll, pay rent, or service bank loan installments. This phenomenon—often termed profitable insolvency or overtrading—is caused by a fundamental failure to understand the difference between accounting profit and operational cash flow.
Discover our CFO Advisory & Financial Management Services.
1. Comparing Profit vs Cash Flow
| Dimension | Accounting Profit (P&L) | Operational Cash Flow (Cash Flow Statement) |
|---|---|---|
| Accounting Basis | Accrual basis (recognizes revenue when earned, expenses when incurred) | Cash basis (recognizes transactions only when funds enter or leave bank) |
| Credit Sales | Included immediately upon issuing an invoice | Excluded until the client actually remits payment |
| Capital Expenditures | Depreciated gradually over years (small current P&L impact) | Deducted immediately in full (massive current cash drain) |
| Debt Repayment | Only interest expense is recorded in P&L | Both principal and interest are deducted in full |
| Purpose | Measures long-term economic viability and tax liability | Measures immediate liquidity, solvency, and day-to-day survival |
2. The Cash Conversion Cycle (CCC) Blueprint
The engine of corporate working capital is the Cash Conversion Cycle (CCC), which tracks how many days cash remains locked in operational workflows:
CCC (in Days) = DSO (Days Sales Outstanding) + DIO (Days Inventory Outstanding) - DPO (Days Payable Outstanding)
Strategic Levers to Compress CCC:
- Reduce DSO (Days Sales Outstanding): Enforce strict 15-day or 30-day payment terms; incentivize early settlement with 1.5% prompt-payment discounts; mandate advance milestones for customized work.
- Optimize DIO (Days Inventory Outstanding): Adopt lean just-in-time inventory practices; liquidate slow-moving stock before it depreciates or incurs warehousing costs.
- Extend DPO (Days Payable Outstanding): Negotiate 45-day to 60-day terms with stable suppliers without incurring interest penalties or damaging vendor goodwill.
3. Real-World Case Study: The Growth Trap
Consider a high-growth software services firm in Kochi that doubles its monthly revenue from ₹20 Lakhs to ₹60 Lakhs in 6 months:
- Paper Performance: Gross margins are 40%, showing an attractive ₹24 Lakh paper profit.
- The Liquidity Gap: The firm hires 15 new engineers (adding ₹12 Lakhs monthly payroll payable on the 1st) and expands office space (security deposit + rent).
- The Catch: Corporate clients operate on 75-day payment cycles.
- The Result: The business must disburse ₹36 Lakhs in operational cash expenses over 3 months before receiving a single rupee from new invoices. Without an overdraft line or equity buffer, the company defaults on salaries despite booming business.
4. Cash Flow Management Rules for Founders
- Maintain a Rolling 13-Week Cash Forecast: Track projected cash receipts and mandatory cash obligations week-by-week. Never rely solely on monthly P&L budgets.
- Segregate Tax Reserves: Transfer GST, TDS, and advance income tax collections into a separate bank account immediately upon receipt. Never use government tax collections as working capital.
- Build an Emergency Liquidity Cushion: Maintain liquid reserves equal to at least 3 months of fixed operating overhead (rent, salaries, utilities).
For comprehensive financial restructuring and cash flow planning, talk to the D BIZ Advisory Team.
Frequently Asked Questions
Akash P R
Business Consultant10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances • D BIZ CONSULTANCY
Business Consultant with 10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances.
Connect with Akash on LinkedInOther Strategic Business Guides
GST Registration Documents in Kerala: How to Avoid Application Rejection
8 min readGST & TaxationGSTR-2B Reconciliation with Purchase Register: How to Match Invoices and Protect ITC
9 min readCompany Law & MCAAOC-4 vs MGT-7: Annual MCA Filing Requirements for Indian Companies Explained
8 min readLLP ComplianceLLP Form 8 and Form 11: Annual Compliance Checklist, Timelines and Late Fee Risks
7 min readLatest Regulatory Bulletins
Speak With Our Senior Business Consultants in Trivandrum & Kochi
D BIZ CONSULTANCY PVT. LTD. provides end-to-end company formation, ROC filings, GST accounting, trademark protection, and statutory compliance. Connect with us for personal advisory at our physical offices or 100% paperless digital onboarding.