57th GST Council Meeting 8 October 2026: Key Decisions and Business Impact
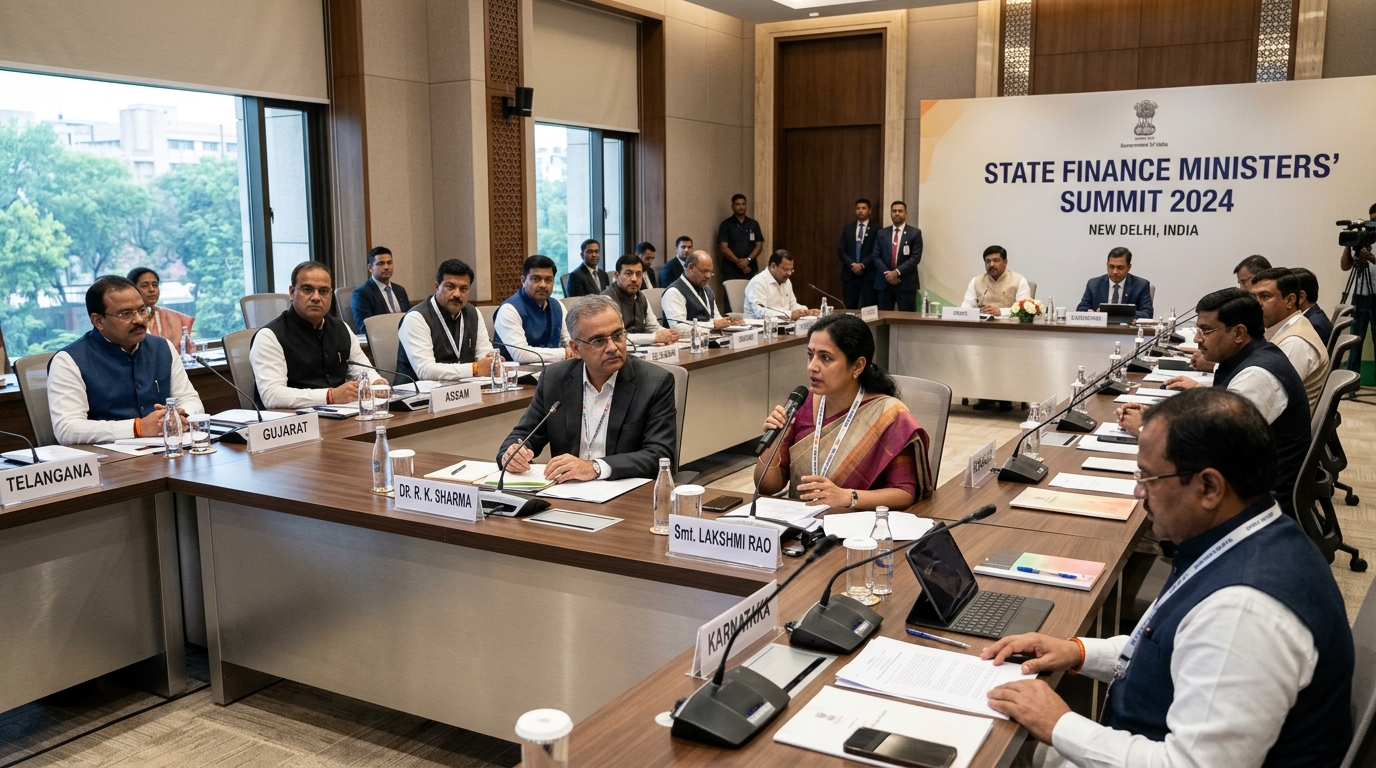
The 57th GST Council Meeting on 8 October 2026 recommended sweeping structural reforms to ease business compliance across India. Key highlights include proposing the repeal of Section 69 arrest powers, raising the prosecution threshold from ₹1 crore to ₹5 crore, automating 90% provisional refunds, liberalizing blocked ITC under Section 17(5) for employee insurance and catering, introducing a ₹10,000 minimum notice threshold, and launching an optional Annual Return Quarterly Payment (ARQP) scheme for B2C MSMEs.
Published Date: 8 October 2026
Editorial Review: Akash P R, Business Consultant (10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances), D BIZ CONSULTANCY PVT. LTD.
News Summary & Quick Answer
The 57th GST Council Meeting, convened on 8 October 2026 under the chairpersonship of Union Finance Minister Nirmala Sitharaman, recommended decisive structural changes to India's Goods and Services Tax framework. Shifting priority from rate revisions to administrative ease and taxpayer confidence, this meeting concentrated on decriminalizing compliance lapses, accelerating working capital liquidity through automated refunds, eliminating unwarranted litigation, and overhauling return reconciliations.
Major GST Council Decisions at a Glance
| Area | Key Recommendation | Detailed Impact Analysis |
|---|---|---|
| Arrest Powers | Proposed complete removal of arrest powers under Section 69 | Read Detailed Analysis |
| Prosecution Threshold | General monetary threshold raised from ₹1 Crore to ₹5 Crore | Read Detailed Analysis |
| GST Refunds | 90% provisional sanction of eligible export & inverted duty refunds automated | Read Detailed Analysis |
| Input Tax Credit | Relaxed Section 17(5) blocked credits on employee insurance, catering, etc. | Read Detailed Analysis |
| Registration & Cancellation | Streamlined Form REG-01 and automated voluntary cancellations | Read Detailed Analysis |
| Return Reconciliation | Enhanced GSTR-1, GSTR-3B, GSTR-2B & IMS alignment effective April 2027 | Read Detailed Analysis |
| Notices & Penalties | ₹10,000 minimum tax demand threshold; general penalty reduced | Read Detailed Analysis |
| Small Businesses & MSMEs | Approved in principle Annual Return Quarterly Payment (ARQP) for B2C firms | Read Detailed Analysis |
| E-Commerce Sellers | Simplified interstate registration utilizing platform warehouses | Read Detailed Analysis |
| Export of Services | Expanded zero-rating scope and rationalized place of supply rules | Read Detailed Analysis |
| Logistics & Transport | Restrictions on unwarranted transit interceptions and sector-specific rates | Read Detailed Analysis |
Complete Breakdown of Key Council Recommendations
1. GST Arrest Powers and Prosecution Reforms
The Council recommended removing the arrest powers under Section 69 of the Central Goods and Services Tax Act, 2017 and increasing the general monetary threshold for launching prosecution from ₹1 crore to ₹5 crore. These landmark steps safeguard legitimate business executives and directors against coercive enforcement in interpretive tax disputes while keeping hardcore fraudulent invoice rackets under statutory scrutiny.
👉 **Read More: GST Arrest Powers and Prosecution Reforms**
2. Faster GST Refunds and Improved Working Capital
To eliminate working capital bottlenecks for manufacturers and exporters, the Council proposed automating electronic cash ledger refunds and introducing a system-based provisional sanction of 90% for zero-rated export and inverted duty claims within 10 days of application.
👉 **Read More: GST Refund Reforms and Business Cash Flow**
3. Changes to Input Tax Credit Eligibility
In a major relief to corporate employers and service industries, the Council proposed diluting Section 17(5) blocked credit restrictions. Qualifying business expenses on employee group health/life insurance, corporate catering, and telecommunication infrastructure will become eligible for input tax credit upon notification.
👉 **Read More: GST Input Tax Credit Reforms Explained**
4. Simplified GST Registration and Cancellation
A modernized, query-free Form GST REG-01 interface with document-selection menus and contextual guidance was approved. Additionally, automated voluntary cancellation of GST registrations will be phased in, eliminating prolonged administrative hold-ups for closing entities.
👉 **Read More: GST Registration and Cancellation Changes**
5. Changes to GSTR-1, GSTR-3B and ITC Reconciliation
The Council recommended introducing a unified return reconciliation framework scheduled for the April 2027 tax period. Featuring enhanced Invoice Management System (IMS) functionality, electronic credit reversal registers, and direct GSTR-1 to GSTR-3B variance reconciliations, this system will systematically resolve reporting discrepancies before notices are triggered.
👉 **Read More: GSTR-1, GSTR-3B and ITC Reconciliation Reforms**
6. GST Notices, Penalties and Appeal Reforms
To unclog tax adjudications, the Council recommended that demand notices under Section 73/74 will not be issued for aggregate tax liabilities below ₹10,000. Furthermore, the maximum general penalty under Section 125 has been slashed from ₹25,000 to ₹10,000, alongside a reduced 5% penalty incentive for prompt payment.
👉 **Read More: GST Notices and Penalty Reforms**
7. Relief for MSMEs and Small Taxpayers
Small retailers and service providers making exclusively B2C supplies with turnover up to ₹5 crore will soon benefit from the Annual Return Quarterly Payment (ARQP) scheme. This will sharply diminish monthly accounting overhead while maintaining quarterly tax remittance cycles.
👉 **Read More: GST Reforms for MSMEs and Small Businesses**
8. E-Commerce Registration Changes
Small digital merchants selling through platforms like Amazon, Flipkart, or ONDC can now obtain state GST registrations by declaring third-party fulfillment center warehouses as their Principal Place of Business under proposed Rule 14B, removing the necessity of maintaining physical rental premises in every state.
👉 **Read More: GST E-Commerce Registration Reforms**
9. GST Export and Zero-Rating Reforms
The Council resolved longstanding cross-border ambiguity by eliminating the restriction on services between Indian head offices and foreign branch establishments, while refining place-of-supply rules for goods delivered inside Free Trade Warehousing Zones (FTWZ) and Special Economic Zones (SEZ).
👉 **Read More: GST Export of Services Reforms**
10. E-Way Bill and Transportation Reforms
To prevent harassment on interstate highways, transit state inspections of moving cargo will be strictly restricted unless initiated under Joint Commissioner approval based on specific intelligence. Key adjustments for EV charging logistics, shared transport, and metal scrap RCM were also tabled.
👉 **Read More: E-Way Bill and Transport GST Reforms**
Actionable Strategy: What Should Businesses Do Now?
- Maintain Current Compliance Frameworks:
GST Council recommendations do not constitute immediately enforceable law. Statutory amendments to the CGST and SGST Acts, Union Budget finance bills, and CBIC notifications must be formally gazetted before altering tax deductions or filing procedures.
- Conduct Comprehensive ITC & Refund Audits:
Review accumulated ITC balances and pending zero-rated refund filings to prepare for automated processing pipelines once portal features activate.
- Audit Supplier Compliance Ahead of April 2027:
Leverage digital invoice reconciliation tools to align sales ledgers with GSTR-2B statements, eliminating mismatches before the mandatory IMS framework rolls out.
- Review Ongoing Show-Cause Notices:
Examine pending tax demands under ₹10,000 and general penalty proceedings with corporate tax advisors to assess potential relief under upcoming transitional amnesty rules.
Impact on Kerala Businesses: Trivandrum & Kochi Commercial Landscape
For enterprises across Thiruvananthapuram, Kochi, Kozhikode, and Ernakulam, these reforms bring measurable operational advantages:
- Technopark & Infopark IT Exporters: Clearer export-of-services definitions will accelerate zero-rated refunds and eliminate cross-border transfer tax disputes for software and engineering firms.
- Vizhinjam Port Logistics & Maritime Trade: Restrictions on arbitrary roadside vehicle detentions will ensure predictable container transit across Kerala's transport corridors.
- Retailers & MSMEs: The ₹10,000 notice cutoff and upcoming ARQP scheme offer welcome insulation against bureaucratic audit scrutiny for traditional merchants and family businesses.
Professional Advisory Support from D BIZ Solutions
Navigating evolving GST regulations requires seasoned corporate guidance. D BIZ CONSULTANCY PVT. LTD. assists businesses with:
- Corporate GST Return Filing & Monthly ITC Reconciliation
- New GST Registration & Multi-State Branch Additions
- Multi-Month GSTR-2A / 2B Consolidation Tool
- Company Registration & Incorporation in Trivandrum
- Corporate Tax Advisory in Kochi
Contact Our Tax Advisory Desks:
- Thiruvananthapuram Head Office: Cotton Hill Rd, Vazhuthacaud, Thiruvananthapuram, Kerala - 695014
- Kochi Corporate Desk: Seaport - Airport Rd, Irumpanam, Thrippunithura, Kochi, Kerala - 682309
- Helpline: +91 8075273408 | Email: business@dbizsolutions.in
Frequently Asked Questions
Practical answers to common business questions regarding this statutory update.
Akash P R
Business Consultant
10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances
D BIZ CONSULTANCY PVT. LTD.
Have questions about this compliance update or require assistance with filing before the due date? Connect directly with our advisory desk:
TC No 44, 913, Cotton Hill Rd, Cotton Hill, Vazhuthacaud, Trivandrum 695014.
Plus Code: GX39+M6 Thiruvananthapuram, Keralam
Koprambil Heights, Seaport-Airport Rd, Irumpanam, Thrippunithura, Kochi.
Other Regulatory Bulletins
GST Arrest Powers Proposed to End: ₹5 Crore Prosecution Threshold Explained
8 OctTax & GSTGST Refund Reforms 2026: Automated Processing and Impact on Business Cash Flow
8 OctTax & GSTGST ITC Changes 2026: Insurance, Catering, Capital Goods and Blocked Credits
8 OctTax & GSTGST Registration and Cancellation Reforms 2026: New Business Benefits Explained
8 OctTax & GSTGSTR-1, GSTR-3B and GSTR-2B Reconciliation Changes Proposed for April 2027
8 OctAvoid Penalties Under Income Tax & MCA with D BIZ
Whether you require Tax Audit Form 3CA/3CB filing by 21 October, Corporate ITR filing by 21 November, or AGM and DIR-3 KYC compliance, our multi-disciplinary team in Thiruvananthapuram and Ernakulam guarantees timely execution.