GST Registration in India: When Is It Compulsory and When Should You Avoid Registering Too Early?
GST registration is not determined only by whether your business is a Private Limited Company, LLP or proprietorship. It depends on factors including aggregate turnover, nature of supplies, place of supply, type of business, specific statutory registration provisions, and whether an exemption applies.
Demystifying GST Registration in India
A common belief among new entrepreneurs is that registering a Private Limited Company or LLP automatically requires immediate GST registration.
However, Goods and Services Tax (GST) is a transaction-based indirect tax regime governed by the Central Goods and Services Tax (CGST) Act, 2017. Registration applicability is determined by:
- Aggregate pan-India annual turnover;
- The specific nature of supplies (goods vs. services);
- Place of supply (intra-state vs. inter-state);
- Mandatory statutory triggers under Section 24; and
- Available product or service exemptions.
What Are the General GST Registration Thresholds?
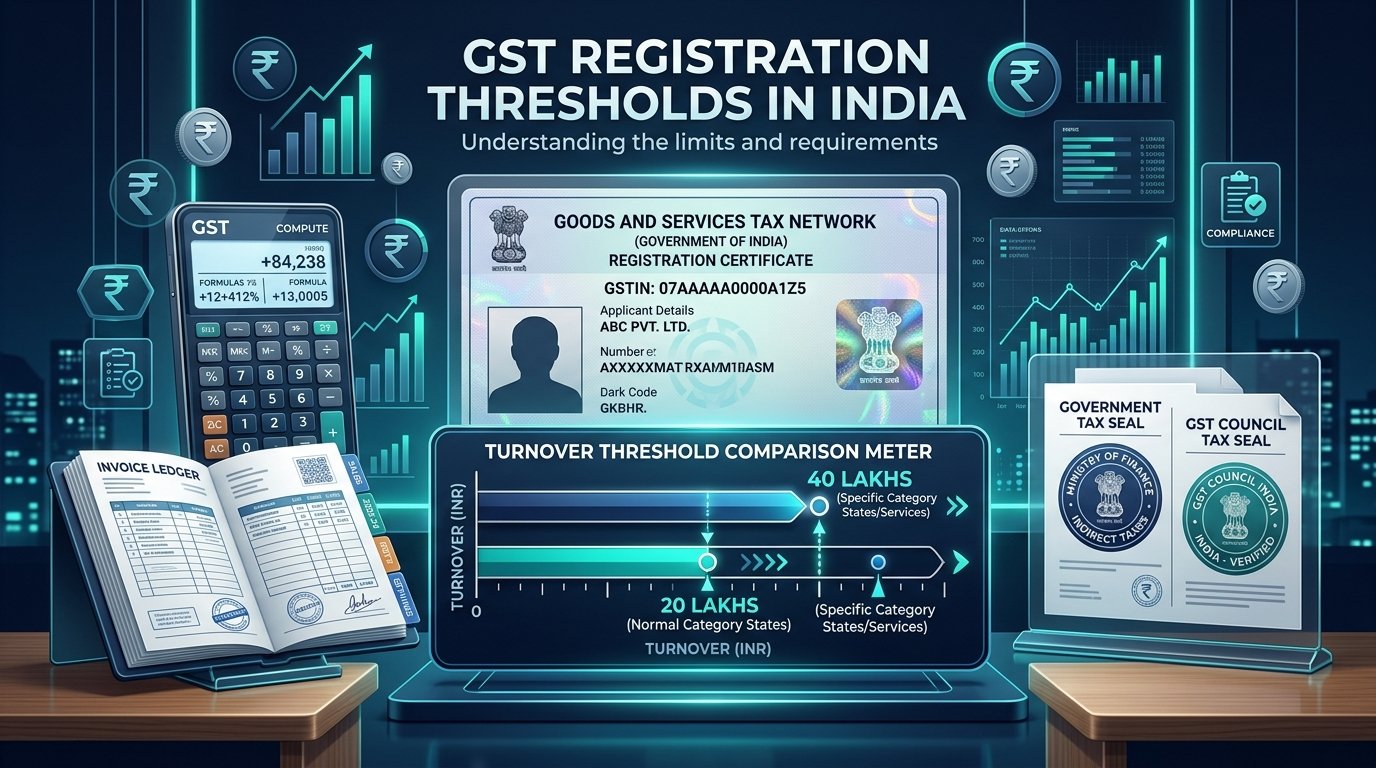
Under Section 22 of the CGST Act, statutory turnover thresholds differ based on whether you deal in goods or services:
- Suppliers of Services:
- The general threshold is ₹20 Lakhs aggregate annual turnover.
- For special category states (such as Manipur, Mizoram, Nagaland, and Tripura), the threshold is ₹10 Lakhs.
- Suppliers of Goods:
- In most states (including Kerala, Karnataka, Tamil Nadu, and Maharashtra), the threshold for exclusive suppliers of goods was enhanced to ₹40 Lakhs, subject to conditions.
- If a business supplies both goods and services under the same GSTIN, the lower ₹20 Lakhs threshold applies.
What Exactly Is Aggregate Turnover?
Under GST law, Aggregate Turnover is calculated on an all-India basis across the same Permanent Account Number (PAN).
It includes the sum total of:
- Taxable supplies;
- Exempt supplies;
- Export of goods and services; and
- Inter-state supplies between distinct business entities under the same PAN.
It excludes inward supplies on which tax is payable under Reverse Charge Mechanism (RCM) and GST taxes (CGST, SGST, IGST).
Crucial Rule: If an entrepreneur operates a software firm, an e-commerce store, and a retail agency under the same PAN across different states, the turnover of all branches is aggregated to determine if the ₹20L/₹40L threshold is crossed.
Compulsory GST Registration Under Section 24: Turnover Does Not Matter
There are specific commercial activities where GST registration is mandatory from the very first rupee of sales, regardless of whether your annual turnover is below the threshold:
- Inter-State Taxable Suppliers: Selling goods across state borders (except certain service providers covered under threshold exemptions);
- E-Commerce Sellers: Anyone supplying goods through an electronic commerce operator (such as Amazon or Flipkart);
- Casual Taxable Persons: Entities carrying out taxable supplies occasionally in a state where they have no fixed place of business (e.g., business exhibitions or seasonal trade fairs);
- Reverse Charge Mechanism (RCM): Persons required to pay GST under RCM;
- Non-Resident Taxable Persons;
- Input Service Distributors (ISD); and
- E-Commerce Operators required to collect tax at source under Section 52.
Should You Opt for Voluntary GST Registration?
Under Section 25(3), any business whose turnover is below the statutory threshold can apply for voluntary GST registration.
#### Commercial Advantages of Voluntary Registration:
- Eligible to Issue Tax Invoices: Enterprise B2B clients generally prefer dealing with GST-registered vendors so they can claim Input Tax Credit (ITC).
- Pass Through Input Credit: You can claim ITC on office computers, software subscriptions, machinery, and vendor expenses.
- Inter-State Market Expansion: Enables immediate trading with partners outside your home state.
#### The Hidden Cost of Registering Too Early:
Once you receive your GSTIN, you become a Normal Taxable Person under GST law. This means:
- You must file monthly or quarterly returns (GSTR-1 and GSTR-3B) without fail;
- Even during months with zero business activity, you must file statutory Nil returns; and
- Failure to file returns attracts statutory late fees (up to ₹50 per day per return) and risks GSTIN cancellation or automated bank attachment notices.
5 Common GST Registration Mistakes
- Incorrect Registered Office Address: Submitting rent agreements or electricity bills with mismatched owner names or inaccurate survey numbers leads to officer queries and on-site physical verification delays.
- Wrong Business Activity / HSN Code Selection: Misclassifying your core services or choosing mismatched SAC codes can lead to scrutiny regarding appropriate tax rates.
- Omitting Additional Places of Business: If you operate a warehouse, godown, branch office, or co-working space, they must be declared in the registration application.
- Registering Without Return Compliance Preparedness: Obtaining a GSTIN without having an accountant or system for monthly filings inevitably leads to late fees.
- Failing to Update GST Records: Any change in authorized signatories, directors, trade name, or operating premises must be updated via core or non-core amendment applications within 15 days.
Frequently Asked Questions
Akash P R
Author & Business ConsultantBusiness Consultant at D BIZ CONSULTANCY
Business consultant and corporate advisor specializing in company incorporation, MCA/ROC statutory compliance, GST advisory, trademark protection, and cross-border structuring across Kerala and India.
Connect with Akash on LinkedInAkash P R
Business & Legal Consultant
D BIZ CONSULTANCY PVT. LTD.
Planning company incorporation, trademark filing, or tax compliance? Speak directly with our consultant:
Springs Tower, Edappazhanji / Paruthippara, Trivandrum.
Plus Code: GX39+M6 Thiruvananthapuram, Keralam
Koprambil Heights, Seaport-Airport Rd, Irumpanam, Thrippunithura, Kochi.
Other Strategic Guides
Private Limited Company Registration in India: 10 Common Mistakes That Can Delay Your Incorporation
7 min readCompliance & AuditCompany Registered – What Next? Essential Compliances During the First 180 Days
6 min readCompliance & AuditPrivate Limited Company Annual Compliance in India: A Practical Checklist for Business Owners
6 min readCompany Law & MCAStarting an Indian Company With a Foreign Shareholder: Incorporation, FEMA and FC-GPR Explained
7 min readLatest Regulatory Bulletins
Tax Audit Report Due Date Extended to 21 October 2026 and ITR to 21 November 2026 for AY 2026-27
28 SeptTax & GSTGSTN Introduces emSigner Version 3.3 for New Digital Signature Certificate (DSC) USB Tokens
27 SeptTrademarks & IPIP India Sets 30 September 2026 as Final Deadline for Mandatory e-KYC Compliance
26 SeptSpeak With Our Senior Business Consultants in Trivandrum & Kochi
D BIZ CONSULTANCY PVT. LTD. provides end-to-end company formation, ROC filings, GST accounting, trademark protection, and statutory compliance. Connect with us for personal advisory at our physical offices or 100% paperless digital onboarding.